Secure Your VA Loan: Free Certificate of Eligibility, Credit Scores from 500!
Dreaming of homeownership? Don’t let credit scores hold you back! Discover how easy it is to access VA loans and get the keys to your perfect home.
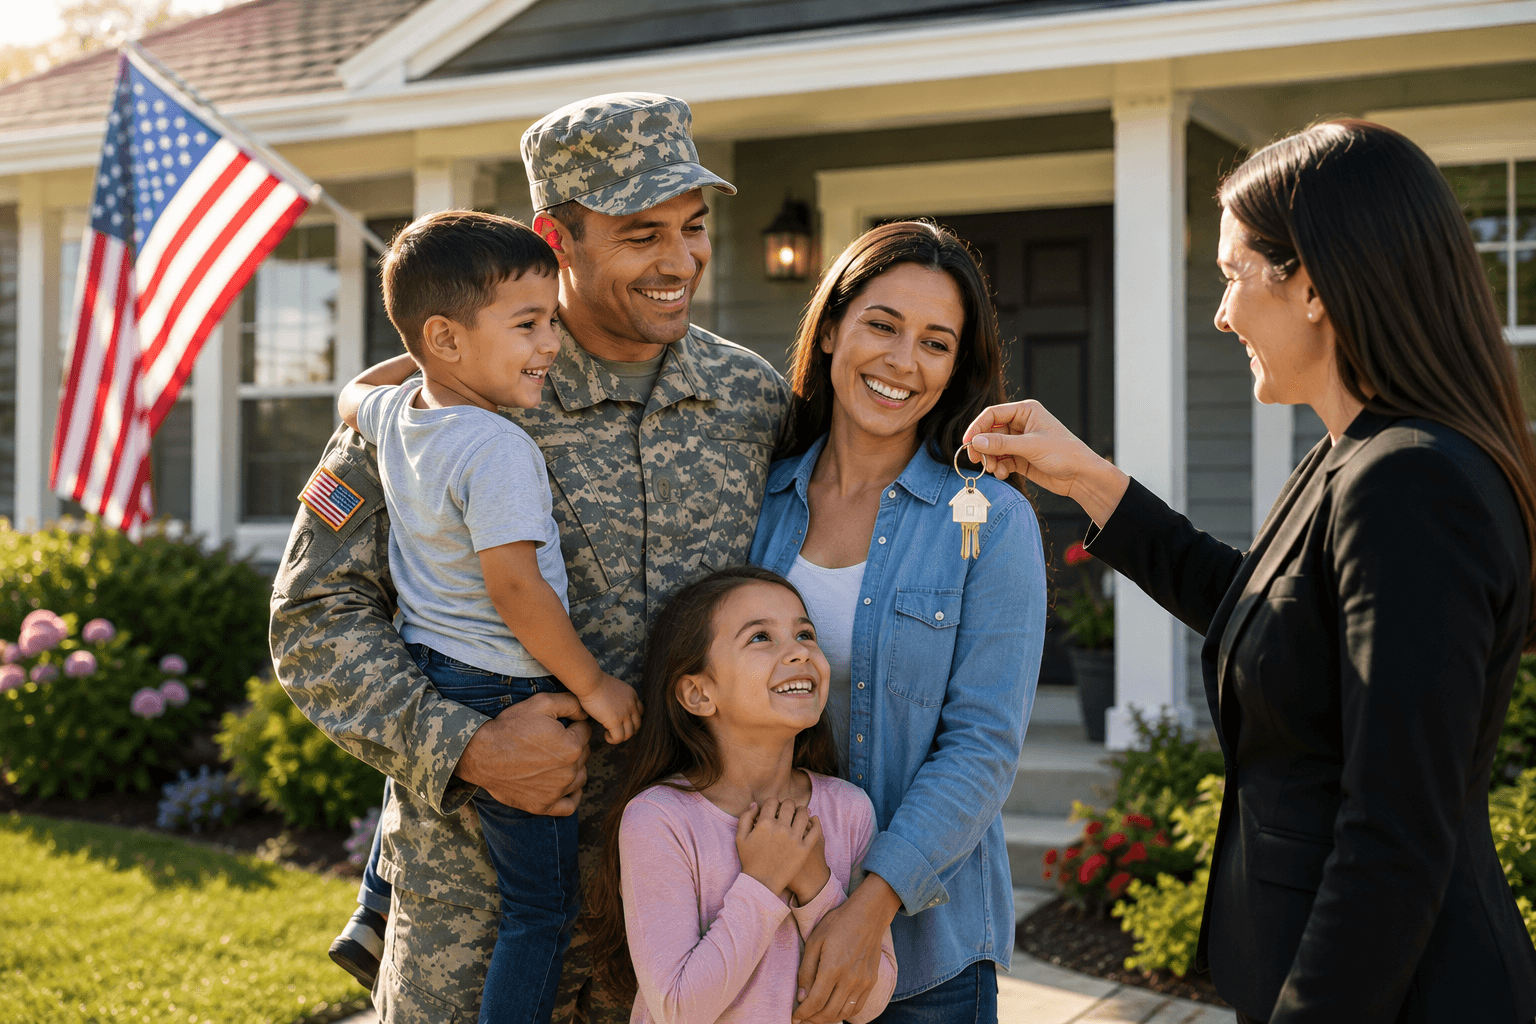
If you’re a veteran or an active-duty service member, you might be wondering how to navigate the world of home financing. One of the best options available to you is a VA loan, which is backed by the U.S. Department of Veterans Affairs. It's designed to help our nation's heroes achieve homeownership with little to no down payment. It's a fantastic benefit, but there’s a particular aspect that is essential to understand: the Certificate of Eligibility (COE) and how it relates to your credit score.
First off, let’s talk about the Certificate of Eligibility. This document is your ticket to unlocking the benefits of a VA loan. It confirms to lenders that you meet the requirements to qualify for this unique financing option. Obtaining your COE is a straightforward process, and the best part? It’s completely free! You can apply for it online through the VA’s website, by mail, or even through your mortgage lender who can help you with the process.
Now, you might be wondering what information you will need to provide when applying for your COE. Typically, you’ll need to share details such as your service history, including your dates of service and type of discharge. For veterans, this could mean showing proof of active duty service, while active service members may just need to include information from their service records. If you were discharged under conditions other than dishonorable, you should be eligible for this certificate.
Once you have your COE, it’s essential to understand how it impacts your ability to secure a loan. VA loans are known for their flexible credit score requirements. While many traditional loans require a minimum credit score often hovering around 620 or higher, VA loans can be available to those with credit scores as low as 500. However, if your credit score falls below 620, you may be required to make a larger down payment. This is a fantastic opportunity for those who may have had financial challenges in the past but are now ready to invest in a home.
So, what does it mean if your credit score is around 500? While it’s certainly possible to qualify for a VA loan with a score in this range, it’s advisable to consider taking steps to improve your credit before applying. A higher credit score can lead to more favorable loan terms and potentially save you money over the life of your loan. Here are some tips to help you boost your score:
1. **Check Your Credit Report**: Begin by obtaining a copy of your credit report. You’re entitled to a free report from each of the three major credit reporting agencies once a year. Review it carefully for any errors or inaccuracies that could be dragging your score down.
2. **Pay Your Bills on Time**: Your payment history is a significant factor in your credit score. Make it a priority to pay your bills on time, as late payments can significantly impact your score.
3. **Reduce Your Debt**: If you have outstanding debts, work on paying them down. A lower credit utilization ratio—how much credit you’re using compared to your credit limit—can positively affect your credit score. Aim to keep this ratio under 30%.
4. **Avoid Opening New Credit Accounts**: While it might be tempting to open new credit lines to increase your available credit, avoid doing this right before applying for a loan. New accounts can temporarily lower your credit score.
5. **Consider a Secured Credit Card**: If you’re struggling with credit, a secured credit card can be a good way to rebuild your score. By putting down a deposit, you can obtain credit and show that you can make payments reliably.
6. **Consult a Credit Counselor**: If managing your credit feels overwhelming, consider speaking with a credit counselor. These professionals can provide personalized advice tailored to your financial situation.
As you work on improving your credit score, it’s also important to understand the other requirements for a VA loan. While the VA does not set a maximum loan amount, lenders may have their own limits based on your creditworthiness and the appraised value of the home you wish to purchase. Additionally, VA loans require a funding fee, which can vary based on your military category and whether this is your first VA loan.
It’s essential to be prepared for the documentation you will need. In addition to your COE, lenders will typically ask for proof of income, such as pay stubs, W-2 forms, or tax returns, to ensure you have the means to repay the loan. Be ready to provide any other documents that might demonstrate your financial stability.
If you’re thinking about tapping into the benefits of a VA loan, or if you have specific questions about your situation—like your credit score or how to obtain your COE—don’t hesitate to reach out. Our team of knowledgeable mortgage loan officers is here to help you navigate the process and provide you with personalized guidance. We understand that every situation is unique, and we’re dedicated to helping you find the best path to homeownership.
Homeownership is not just a dream; it’s an attainable goal, especially with the benefits of a VA loan. Let us assist you in securing your future and making your homeownership dreams a reality. Contact us today to discuss your specific needs and get started on your journey to owning your home.